Jodie Sweetin says no one on Fuller House knew she was down to $190 in her bank account
Jodie Sweetin says she borrowed money during her first week on Fuller House and reached her first pay cheque with about $190 left.

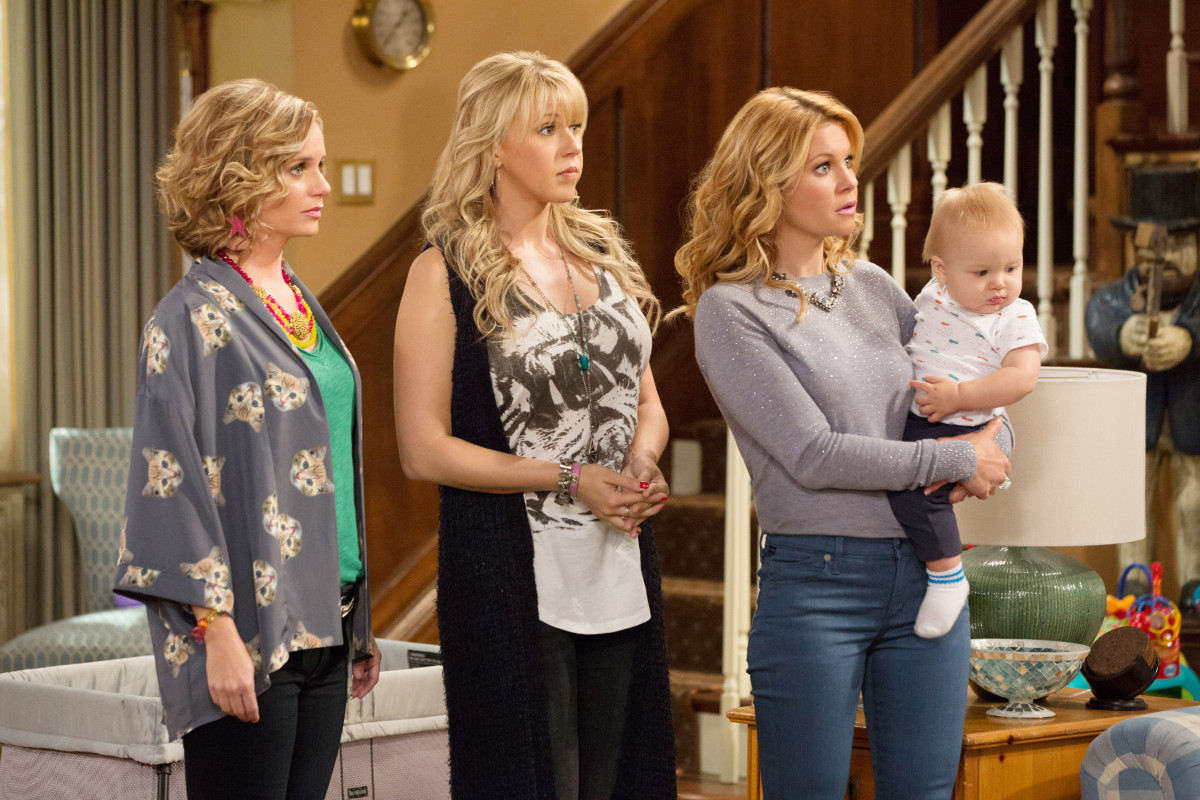
Jodie Sweetin says her return to one of TV’s best known sitcom families looked very different behind the scenes. While she was stepping back into Stephanie Tanner’s world, she was also trying to stretch about $190 in her bank account until her first Fuller House pay cheque arrived.
Sweetin shared that she had to borrow money during her first week working on Fuller House. She said she got through to that first pay cheque with roughly $190 left, and added that none of the people she was working with knew how tight things were.
That detail gives a very different frame to what, on screen, looked like a major television return. Fuller House brought back a large part of the original Full House ensemble for Netflix, with Sweetin again playing Stephanie Tanner. The revival went on for five seasons and nearly 80 episodes, but Sweetin says her financial position at the start was far less secure than viewers might have assumed.
What she said about work, money and humility
Sweetin also spoke about a period when addiction had left her with no money. She said that reality pushed her to look beyond Hollywood work and take jobs outside the entertainment business.
She made clear that she did not feel above doing what she described as a normal job. Her focus, she said, was simply covering her bills and supporting her children. According to Sweetin, other people sometimes reacted with surprise to seeing her in that kind of role, but she saw it much more plainly. It was work, and it paid.
She also described the kind of everyday moment that showed her how much had changed. Sweetin said there were times at Target when she had to turn around and put items back because there was not enough money available on her debit card. She said experiences like that taught her humility.
From Full House child star to Netflix revival
Sweetin first became famous as Stephanie Tanner on Full House, which ran for eight seasons from 1987 to 1995. Fuller House later reunited several original cast members, including Candace Cameron Bure, Andrea Barber, Scott Weinger, Bob Saget, Lori Loughlin, Dave Coulier and John Stamos. Mary-Kate and Ashley Olsen did not return.
The reboot also featured Juan Pablo Di Pace, Adam Hagenbuch, John Brotherton, Michael Campion, Elias Harger and Soni Bringas.
What stands out in Sweetin’s account is the gap between public perception and private reality. Even while walking back onto a familiar set tied to a hugely recognisable show, she says she was quietly dealing with the kind of financial stress that meant borrowing money, watching every purchase and making it through until the next cheque landed.
Why public success does not always mean financial security
A well known face on screen does not automatically mean someone has steady money coming in. Acting income is often uneven. One project can pay well, then there may be long gaps with little or no work. Pay can also be split across different stages, so money that looks large on paper may not arrive all at once.
There are also costs people do not always see. Performers may pay for agents, managers, travel, training, childcare, housing in expensive cities, and taxes that are not taken out automatically. Some income can come later through repeat showings or other rights, but that varies a lot and is not guaranteed to cover everyday bills. It is possible to look successful and still have cash flow problems.
How irregular income affects everyday life
Irregular income makes budgeting harder because rent, food, utilities and debt payments tend to be fixed, while work is not. A bank balance can drop quickly between jobs, especially if spending has been built around better months rather than lean ones.
One useful approach is to treat your lowest reliable month as the base for your budget. Keep essential bills in one account and move money for non essentials to another, so day to day spending is easier to control. If your work is freelance or unpredictable, setting aside money for tax as soon as you are paid can prevent a bigger shock later. Many people also find it helpful to build a buffer for basic costs before spending on lifestyle upgrades.
What to do if your balance is getting dangerously low
If money is tight, act early rather than waiting for missed payments. List essentials first: housing, food, utilities, transport to work, and medication. Then contact lenders, landlords or service providers and ask about temporary hardship options, payment plans or due date changes. Many companies are more flexible before an account falls behind.
Check whether your area offers support with food, bills, housing or income replacement, because help varies by country and local rules. If debt is part of the problem, a reputable debt adviser or financial counsellor can help you prioritise what to pay first. Even a simple plan, cutting automatic renewals, pausing non essential spending, and asking for help quickly, can create breathing room.